Historical Current VII
2018–2020
Building Through the Bear Market
The market had changed its mind. Bitcoin still had work to do.
Explore the history ↓The visible story / 2017–2018
The price fell.
The story did not end.
- Late-2017 peak
- ≈ $19,800
- December 14, 2018 · Bitstamp
- $3,200
Below the market / 2018–2020
Parallel histories, not an inverse price/development relationship. Releases, experiments and institutional access did not guarantee adoption or survival.
Documents, experiments, unfinished possibilities.
Follow the narrative; open a document to look closer.
01 / Chapter 1
The Quiet After the Argument
The market had changed its mind. Bitcoin still had work to do.
By the beginning of 2018, Bitcoin had survived an extraordinary argument about what it should be. The dispute over scaling had exposed disagreements about the rules of the network, the legitimacy of changing them, and who possessed the authority to speak for a system designed without a central administrator. Segregated Witness had activated in August 2017. Bitcoin Cash had separated from Bitcoin. An effort to produce a further change through SegWit2x had been abandoned. The consequences did not vanish when the argument subsided. They remained in software, businesses, relationships and public expectations.
A different argument now dominated attention. Bitcoin's price, which had approached $20,000 in December 2017, declined severely during 2018. By mid-December it was trading at a small fraction of its peak. Speculators, miners, businesses and people who had bought during the boom faced different versions of the same problem: a market that no longer rewarded enthusiasm simply for being enthusiasm.
It would be tempting to describe the next three years as a hidden reconstruction, concealed beneath financial disappointment. But concealment suggests that a clear master plan existed. There was no such plan. Bitcoin was an open network whose participants had different incentives and different definitions of progress. A miner calculating electricity costs, a developer reviewing consensus code, an exchange integrating new address formats and a merchant trying to avoid payment intermediaries were responding to different pressures. Their work occasionally reinforced each other. It could also produce conflicting demands.
The market decline did matter. It damaged firms dependent on speculative volume, made expansion and financing harder, and changed the public conversation. Yet a falling exchange price did not erase the technical properties of a valid Bitcoin transaction. Nor did the continuation of technical work establish that demand for every new product would eventually materialize. These were separate facts, too often folded into a single story.
The most useful way to enter this period is therefore through an apparently modest question: after Bitcoin acquired new technical capacity during the Scaling Wars, would the people operating the network actually use it? A rule change establishes what the network permits. It does not rewrite every exchange, wallet, payment processor or user's habits overnight. In 2018, this distinction between protocol capability and practical implementation became a central feature of Bitcoin's evolution. [1] [3]
02 / Chapter 2
Using What Had Been Won
Activation was the beginning of deployment, not its end.
SegWit had become part of Bitcoin's consensus rules in 2017, but much of the economic network still needed to make practical changes to benefit from it. Wallets had to create and recognize appropriate outputs. Exchanges had to adapt systems that were often designed around older address types and conservative payment-processing workflows. The efficiency gains depended in part on how transactions were constructed, batched and signed—not only on whether SegWit existed in the rules.
Bitcoin Core 0.16.0, released on February 26, 2018, demonstrated the difference. It introduced full SegWit support in the wallet and user interfaces, including native SegWit Bech32 addresses beginning with bc1. These addresses were not a new currency or a new network. They were a way to take advantage of the already activated SegWit structure, with a format intended to make mistakes easier to detect. The release also introduced default hierarchical deterministic wallets for newly created wallets and other changes to ordinary operation.
This was development without spectacle. To a reader watching only the price chart, an address format could appear inconsequential. To a business moving large numbers of payments, implementation choices influenced fees, operational complexity and the reliability of sending funds. The economics of using Bitcoin depended partly on whether businesses adopted the available techniques.
That problem became the stated mission of Bitcoin Optech. In July 2018, the group publicly described its goal as helping Bitcoin companies use existing techniques more efficiently, including SegWit, transaction batching, fee estimation and coin selection. Optech's own framing was deliberately practical. It was interested in future work such as Lightning and Schnorr signatures, but its immediate concern was with capabilities businesses could deploy already.
The historical distinction matters. An engineering proposal can be elegant, a software release can be substantial, and a service provider can still fail to deploy it. Bitcoin's maturation therefore involved something less dramatic and harder to measure than a new consensus rule: coordinating practices across organizations that possessed no obligation to follow a common roadmap. Optech's work made that operational problem explicit. [1] [3]
03 / Chapter 3
The Bug That Could Have Broken the Limit
The most consequential code change of the year was an emergency repair.
On September 17, 2018, developers received a report of a bug in Bitcoin Core. Initially understood as a denial-of-service problem—a way to crash affected software—the defect proved more dangerous. In affected versions, a miner able to construct a particular invalid block could potentially exploit faulty handling of duplicate transaction inputs to create coins outside Bitcoin's intended issuance rules. The risk touched one of the network's defining assurances: that valid software would reject attempts to exceed the monetary schedule.
The contemporary disclosure offers an unusually detailed view of how developers responded. The report reached several prominent contributors. Matt Corallo identified the inflation dimension the same day. Developers prepared a patch, contacted mining and business operators, coordinated upgrades and publicly urged users to install fixed software. Bitcoin Core 0.16.3 became available on September 18. The more serious inflation implications were disclosed publicly on September 20, after an initial emphasis on the denial-of-service aspect helped create time for remediation.
The distinction between vulnerability and exploitation is essential. The developers' disclosure stated that they were unaware of any attempts to exploit the defect. The episode was not a documented theft and did not establish that Bitcoin's supply actually increased. It established that software entrusted to enforce the supply rules had contained a serious consensus-related weakness, and that the surrounding community needed to respond rapidly.
This was a revealing test of the post-Scaling Wars system. Developers could review and release a fix, but they could not simply command every independently operated node to upgrade. Miners and businesses had to evaluate warnings, trust their sources, download patches and change running systems. The response depended on relationships and informal coordination even though no organization possessed the formal right to change Bitcoin's monetary rules alone.
The vulnerability also resists two convenient historical conclusions. It disproves any suggestion that several years of operation made Bitcoin's implementation immune to a catastrophic bug. But the successful emergency response, in the absence of a known exploit, is equally part of the record. The period's resilience came not from an inability to fail, but from the practical and sometimes fragile capacity to detect, communicate and repair dangerous mistakes. [4]
04 / Chapter 4
A Payment That Never Reached the Blockchain
Lightning moved from demonstration toward real money, without becoming ordinary money.
Bitcoin's ledger was designed to let participants verify transfers without needing a bank to authorize them. That security model has a cost. Every ordinary on-chain payment competes for space in a global system whose blocks have limited capacity. The 2017 period had made transaction congestion and fees a subject of public argument. Lightning proposed a different arrangement: two parties could lock funds into a channel and then update their balances through signed commitments without recording every intermediate payment on the blockchain.
Opening and eventually closing the channel involve Bitcoin transactions. The changes inside the channel happen between the parties, protected by a protocol that allows disputes to be resolved with Bitcoin's base-layer rules. For longer routes, a payment can cross several channels without requiring the sender to maintain a channel directly with the eventual recipient. In theory, this could enable faster, smaller payments while reserving limited block space for settlement and channel management.
The theory was not the same as a service ordinary people could safely use. On March 15, 2018, Lightning Labs announced lnd 0.4-beta, describing it as its first Lightning mainnet beta. The release permitted use with real Bitcoin, but the company addressed developers, technically sophisticated users and prospective routing-node operators. It expressly advised users to experiment with small amounts. That warning is not a minor footnote; it reveals the maturity of the system at the moment it crossed a symbolic threshold.
The period also featured implementations from independent teams, including c-lightning and Eclair. Interoperability mattered because Lightning was intended to be a network rather than a single company's proprietary payment product. A channel opened by one software implementation should be able to participate in a wider system that other software could understand. Achieving that required not only specification work but debugging and security cooperation among independent developers.
Early demonstrations made Lightning's possibilities visible. A payment could be completed without creating a new Bitcoin transaction for every hop. Yet what appeared instant in a demonstration could require difficult preparation: maintaining a funded channel, having enough spendable balance in the right direction, finding a usable route and managing a node that might need monitoring or recovery. The experiment established a real technical direction. It did not establish that Bitcoin had solved retail payments. [2]
05 / Chapter 5
Liquidity Is Not a Button
The hard part of paying across a network was knowing where the money could move.
A Lightning payment could travel across a chain of intermediaries without requiring the sender and recipient to open a direct channel. The appealing sketch was simple: Alice pays Bob, Bob forwards value to Carol, and no intermediary is meant to be trusted with a free option to keep the money. The reality was harder. Each channel had a fixed amount of bitcoin locked into it, with a changing distribution between its two participants. A route could exist on a map yet lack enough spendable balance in the necessary direction.
This was especially frustrating for newcomers trying to receive a payment. Opening a channel and funding it from one's own wallet ordinarily made it possible to send through that channel, not automatically to receive an equivalent amount. Receiving required someone else to have usable outbound capacity toward the recipient, or the recipient to arrange incoming capacity. Channel liquidity was not a preference hidden in a settings menu. It was part of the economic condition of a payment path. A routing node also needed to remain available, maintain a current picture of channels, protect secret material and collect fees without charging so much that a payment became impractical.
Security risks followed directly from those mechanics. Lightning commitments were presigned settlement transactions: if a participant disappeared or cheated, its counterparty needed the ability to enforce the appropriate channel state on Bitcoin's base chain, sometimes within a time limit. Fees could change while those transactions sat unbroadcast. A transaction with too low a fee could fail to confirm promptly just when confirmation mattered most. The 2019 discussion of simplified commitments, which developed into anchor-output designs, was not cosmetic optimization: it concerned whether channel participants could increase fees on their closing transactions when conditions changed. By 2020, implementations were experimenting with these approaches, but broader dependencies and adversarial issues remained unresolved. [24] [25]
The period was also marked by software vulnerabilities. In January 2019, Bitcoin Optech warned of a C-Lightning release correcting a remote denial-of-service problem that could crash a node and, in some circumstances, expose funds to theft. In October 2020, LND maintainers urged operators to upgrade before researchers publicly described two distinct vulnerabilities affecting older versions. Bitcoin Optech's subsequent coverage reported that both could permit theft from affected Lightning nodes. This was not a report that Bitcoin's base-chain consensus had failed, nor proof that every Lightning user lost money. It was evidence that the software protecting payment channels was still confronting difficult security assumptions. [26] [27] [28]
Some difficulties were less dramatic but just as revealing. Payment probing could reveal information about channels; unannounced channels were not automatically private in every sense; channel-jamming attacks threatened to occupy scarce payment capacity. Developers were working on route finding, backup techniques, watchtowers, payment secrets and fee mechanisms in a system that required both cryptography and everyday operations to succeed. Payment failures, security advisories and operator education were part of the transition from successful demonstrations to a network on which strangers could safely depend.
By late 2020 Lightning had unquestionably advanced beyond its first mainnet beta. It had not become a frictionless replacement for on-chain payments or ordinary electronic banking. Its history is most faithfully told through the distance between a payment's mathematical promise and the practical conditions necessary to make it reliable.
06 / Chapter 6
The Merchant Can Run the Server
Payment infrastructure was also a question of who held the money.
A shop that accepts Bitcoin needs more than an address. It needs to present invoices, recognize payments, manage records, reconcile orders and decide how to handle changing prices. Commercial processors can provide these functions, but they also introduce their own accounts, policies and service dependencies. BTCPay Server offered a different approach: businesses and individuals could run open-source payment infrastructure under their own control.
BTCPay began in 2017, before the period covered by this Current. Its significance in 2018–2019 came from development into a broader self-hosted payment toolkit and from a growing support community. In September 2019 the project announced a foundation and a grant from Square Crypto. In the project's own account, volunteer work, merchant use and open-source funding were central to its development.
This offered a concrete alternative to custody by a conventional payment intermediary. A merchant could operate payment-processing tools without surrendering the underlying Bitcoin to the software provider. But independence carried obligations: someone still needed to operate the system, secure keys, maintain a server or choose trusted hosting, handle support and manage accounting. Free software did not mean effort-free commerce.
The broader historical importance lies in how this work reframed merchant adoption. Counting the number of companies that announced Bitcoin acceptance was a poor measure of whether people could use Bitcoin meaningfully in everyday exchange. Operational control, reliable invoices and recoverable custody might matter more than a promotional sign. As financial firms built increasingly centralized access points, others built tools allowing users to remain their own payment operators. Those developments were not opposites in every respect, but they embodied distinct ideas about what Bitcoin was for. [9]
07 / Chapter 7
Making a Signature Travel
Self-custody became a problem of coordinating people, devices and backups.
A Bitcoin wallet did not need to belong to an exchange for its owner to encounter a custody problem. A person holding a meaningful amount of savings needed to know more than where the private key was stored. They needed a way to verify what the key would sign, to reconstruct the wallet after a lost device, and to arrange access when its owner was unavailable. For families and institutions, protecting a single secret could become an uncomfortable concentration of risk.
One answer was to require several keys rather than one. A two-of-three multisignature wallet, for example, could permit spending with any two of three designated signers. The loss of one key would not necessarily destroy access; the theft of one key would not necessarily confer control. Yet the protection existed only if the backups, key locations, wallet configuration and recovery instructions were truly independent. A user could preserve all three keys and still lose access by failing to preserve the information needed to reconstruct the wallet.
The software challenge was that different signing devices and wallet applications needed a common language. BIP 174, originally created in 2017, specified Partially Signed Bitcoin Transactions (PSBTs): portable records containing the information a signer needs to inspect and authorize a transaction. Bitcoin Core 0.17.0, released in October 2018, exposed PSBT operations. The transaction could be prepared on one computer, passed to a signing device kept separately, and returned for combination and broadcast. The standard did not decide whether a particular transaction was safe; it made cooperation among independently operated components possible. [5] [6] [71]
Other work addressed the information a wallet must remember. Output script descriptors provided a way to describe which scripts and keys a wallet was watching. Miniscript, discussed publicly in 2019, offered a more structured way to describe and analyze spending conditions. Hardware Wallet Interface (HWI) worked on communication between Bitcoin Core and external signing devices. These advances did not instantly produce easy consumer software. They were pieces of a system whose safety depended on correct implementation and human use. [29] [30] [31]
In 2018 and 2019, Casa tried to make that system into a repeatable service. Its Keymaster product combined personal key management with multisignature arrangements and supported hardware wallets. Its 2019 retrospective reported expansion into a basic two-of-three setup, greater hardware-wallet integration, and an announced inheritance initiative called Casa Covenant. These were the company's contemporaneous descriptions of products and plans; an announced inheritance protocol must not be mistaken for proof that every customer's heirs could already recover Bitcoin successfully. [69] [72]
A further lesson came in early 2020. Casa announced that it would stop building new plug-and-play nodes and redirect its attention to software and key management. That was a business decision, not a Bitcoin consensus change. It nevertheless demonstrates the difference between selling a device that made running Bitcoin infrastructure easier and building a sustainable service around the enduring difficulty of custody. There were real choices about which friction customers would pay to remove. [70]
The independent open-source path mattered too. Specter Desktop set out to place a graphical interface around Bitcoin Core, hardware devices and multisignature setups. Its public documentation expresses the central obstacle plainly: Bitcoin Core could perform these operations, but much of the experience remained command-line oriented. The presently accessible documentation has been revised over time, so it cannot alone establish which device models or features were supported in 2020. Those details must be checked against date-specific release tags before appearing in the finished chapter or a reconstructed period interface. [73]
The deeper historical change was that self-custody was moving beyond the instruction to hide a seed phrase. It was becoming a practical discipline of independently verifiable transactions, multiple devices, explicit wallet policies and recovery arrangements. Every additional safeguard brought its own maintenance burden. In that tension—between freedom from an intermediary and responsibility for everything the intermediary once managed—the bear-market years exposed one of Bitcoin's most persistent human design problems.
08 / Chapter 8
Privacy Has an Adversary
The ledger could be independently verified. So could the habits of the people using it.
A Bitcoin address is not a person's name. Yet the ledger records the transfers between addresses for anyone to examine. A customer who reuses addresses, combines coins received at different times, or moves money through an exchange that knows their identity can create evidence linking previously separate parts of their financial life. Bitcoin's transparency protects public verification of supply and transactions while raising a different question: who can reconstruct private economic behavior from that same evidence?
In 2018 the designers of Wasabi Wallet approached one part of this problem with a practical transaction-construction technique: CoinJoin. Rather than sending coins individually in a way that makes ownership relationships relatively straightforward to infer, several users assemble a joint transaction with multiple inputs and outputs. Equal-sized outputs can make it harder to determine which participating input paid which output. Wasabi's 1.0 release arrived on October 31, 2018. But the important historical achievement was not invisibility; it was putting a privacy technique into a product ordinary motivated users could try, while accepting that its protection depended on how transactions were formed and spent afterward. [8] [39]
Samourai Wallet pursued another approach. Its Whirlpool service and related spending tools used coordinated transactions and strategies for keeping unmixed change separate from mixed outputs. In June 2019, Samourai made Dojo available as open-source software so a user could connect a wallet to infrastructure under their own control. That addressed an often-overlooked privacy problem: a wallet can generate locally held keys yet still reveal address and transaction information to the servers it relies upon. Dojo could reduce that reliance, but operating additional infrastructure added setup and maintenance burdens. Contemporary reporting documents the release, not widespread installation or proven anonymity for every user. [40] [41]
What makes a transaction private depends on what the observer already knows. CoinJoin can frustrate the simple assumption that all inputs in a transaction belong to one individual, but analysis of deposits, withdrawals, change outputs and later spending can recover useful relationships. A study first circulated in 2021 and drawing on blockchain observations extending through February 2022 found both identifiable CoinJoin activity and limits from pre- and post-mixing traceability. The results can help a later historian evaluate the techniques, but its cumulative usage figures cannot be assigned to 2020 and the study is not evidence that any named user was identified in 2019. [42] [63]
Another path emerged from an older idea called Pay-to-EndPoint. Instead of creating a special transaction with several people who wish to mix coins, a normal payment can include an input from the receiver as well as the sender. This payjoin construction weakens a prominent surveillance heuristic: the assumption that the same person controls all transaction inputs. In April 2020, BTCPay Server added sending and receiving support; BIP78 then formalized the design for interoperability. This connected privacy to an ordinary payment workflow rather than only to specialist mixing activity. The same distinction between a technical implementation and broad user adoption still applied. [43] [44]
There was no technical conclusion that 'privacy had been solved' by the end of 2020. Coordinators could create privacy and availability tradeoffs; users could reveal information through exchanges; fees and participant availability could limit practical mixing; and observers could continue improving their techniques. Some privacy-specific services later became the subjects of legal proceedings, which should be described in a separately dated retrospective rather than read backward as proof of wrongdoing by every user. The period's historical development was a widening range of possible defenses against financial surveillance, and an increasingly explicit realization that self-custody did not automatically mean informational independence.
09 / Chapter 9
A Different Kind of Sidechain
Faster settlement could be purchased with a different arrangement of trust.
Moving Bitcoin from one trading venue to another could expose firms to delays, custody relationships and changing market prices. Blockstream's Liquid Network addressed that problem with a sidechain whose members could transfer a Bitcoin-linked asset, L-BTC, under a federated operating model. Blockstream records the network's first block on September 27, 2018, and its public launch announcement on October 10.
Liquid was not an upgrade of Bitcoin's consensus rules, and it did not inherit every property of the base layer unchanged. A participating federation operated essential parts of the system. That design enabled different settlement and confidentiality features, but it also created governance and operational dependencies different from those faced by a person verifying ordinary Bitcoin blocks with their own full node.
The distinction mattered because several approaches to scaling emerged from the same underlying pressure. Lightning relied on channels and the ability to enforce their outcomes on Bitcoin. Liquid created a separate ledger operated through federation. Payment processors could instead offer more convenience by managing funds for customers themselves. These designs could all move value, but they placed control, monitoring and failure risk in different places.
A Liquid transfer also should not be mistaken for a native on-chain BTC transfer. A user relies on the sidechain's peg and federation to move between the two systems. Confidential transaction features can shield amounts within that environment while changing the trust model from independent base-chain verification.
A launch announcement establishes that an infrastructure network began operating. It does not measure how much economically meaningful settlement followed. Liquid belongs in this Current because it makes the widening menu of Bitcoin infrastructure choices visible—not because every enterprise settlement problem was solved in 2018. [7]
10 / Chapter 10
The Gatekeeper Fails
The claim that coins were trapped behind a dead man's passwords concealed a more devastating explanation.
When customers of Canada's QuadrigaCX exchange found themselves unable to withdraw their funds in early 2019, a strange explanation dominated international coverage. The platform said its chief executive, Gerald Cotten, had died in India in December 2018, taking with him critical access to its digital assets. The episode seemed to illustrate a paradox of cryptocurrency custody: the protective secrecy of private keys could become catastrophic when one individual alone controlled them.
The chronology quickly grew more troubling. Quadriga announced Cotten's death in January 2019; it stopped operating and sought creditor protection in February. Customers had entrusted the platform with both conventional money and crypto assets. Their account balances were promises made by the exchange, not individually verified proof that the platform still held sufficient assets. When withdrawals stopped, users had little independent means to inspect what lay behind those promises. [32]
On June 11, 2020, staff of the Ontario Securities Commission published an extensive investigation that fundamentally changed the public account. The OSC staff concluded that the platform's collapse resulted principally from fraud committed by Cotten, rather than from a simple loss of private keys. Their review found that he created accounts under false names, assigned fictitious money and crypto balances to those accounts, and traded against actual customers. Trading losses left a hole in the assets available for withdrawals. Staff also found unauthorized trading with customer assets on outside platforms and personal misuse of funds. [32] [33]
The scale was grave. According to the OSC staff report, over 76,000 clients were owed assets valued at approximately C$215 million when Quadriga entered creditor protection. Only approximately C$46 million in assets had been recovered or identified, leaving losses of at least C$169 million. Those totals concern customers' combined fiat and cryptocurrency exposures, not exclusively Bitcoin. The report was an OSC staff investigative assessment, not a court judgment or finding of an OSC hearing panel; its findings are attributed to staff rather than stated as an adjudicated verdict. [62] [32]
These details matter because they challenge a misleading moral. The failure was not simply that one man forgot to share a password. It was that one man had gained extraordinary discretion over other people's assets while operating without meaningful segregation, accounting or supervision. The exchange's internal account screen could still tell a customer that money was present even when the corresponding assets were missing. Bitcoin's public blockchain did not make Quadriga's internal liabilities or Cotten's conduct transparent to its customers.
Quadriga was not the only point of failure. On May 7, 2019, Binance reported a theft of approximately 7,000 BTC from a hot wallet following a sophisticated compromise that involved user credentials and other information. Binance's report concerned a breach of exchange custody and controls, not Bitcoin's supply rules or transaction validation. Yet for the people whose ability to trade or withdraw depended on exchanges, the distinction between a reliable decentralized network and an unreliable intermediary was anything but academic. [10]
The larger story of the bear market therefore has an unsettling symmetry. Engineers were giving people additional ways to hold and authorize Bitcoin without trusting an intermediary, while many people continued to choose—or had little practical alternative to—platforms that pooled control. Neither route eliminated risk. Self-custody could fail through mistakes or lost recovery material. Custodial exchanges could fail through fraud, hacking, insolvency or inaccessible accounts. The relevant historical question was who controlled the assets, who could verify the promises, and who bore the loss when those promises failed.
11 / Chapter 11
The Rails Before the Train
Financial access could become more formal long before demand was proven.
Financial institutions did not encounter Bitcoin for the first time in 2018. The transformation under examination was narrower: companies began announcing or delivering custody, execution and regulated market products designed for clients who could not easily operate as hobbyists. Fidelity announced plans for a dedicated digital-assets service in 2018. In 2019 it received a New York limited-purpose trust charter. Those were distinct institutional stages: a stated intention, a regulated entity, and the subsequent operation of services cannot be treated as one event.
Bakkt supplied an instructive second case. Its physically settled Bitcoin futures were scheduled by ICE Futures U.S. to begin trading on September 23, 2019, using clearing and warehouse arrangements familiar to sophisticated markets. A physically settled contract requires delivery of Bitcoin under the contract's terms rather than simply paying a cash difference. It is a form of market infrastructure, not a guarantee that traders will use it in great numbers.
Contemporary reporting noted thin first-day trading. That detail is not an embarrassing aside to be removed from a story about maturation. It demonstrates why institutions can construct a new product before a market has decided how valuable it is. Financial legitimacy can include legal clarity, custody procedures, segregation of responsibilities and accounting infrastructure, none of which should be confused with immediate liquidity or a broad base of users. The relevant archival contrast is especially stark: Fidelity announced institutional services in 2018 and reported its New York trust charter in 2019, whereas Bakkt's actual trading start had a publicly observable opening day. A charter or warehouse process verifies regulatory and operational readiness, not the scale of future customer participation. [64]
The financial sector's gradual accommodation of Bitcoin therefore had two separate chronologies: building access and watching people choose whether to use it. Both mattered; neither promised the outcome of the other.
12 / Chapter 12
Bitcoin Meets the Rulebook
Freedom to transact did not eliminate the laws governing businesses around transactions.
Bitcoin's software permits two parties to exchange value without asking a payment processor to create the transaction. That does not mean every business facilitating access to Bitcoin operates outside law. Exchanges, custodians and intermediaries handle customers, accounts, records and often national currencies. The 2018–2020 period showed governments attempting to fit these activities into financial rules designed for very different institutions.
In June 2019 the Financial Action Task Force issued guidance concerning virtual assets and virtual-asset service providers. Its scope was broader than Bitcoin. Its significance to Bitcoin lay in the compliance demands for regulated intermediaries that bought, held or transferred it for customers. The result was a tension, not a contradiction: the base network could remain permissionless while the easiest points of access acquired obligations to identify users and exchange information.
India demonstrated that legal boundaries could also move sharply. The Reserve Bank of India had directed regulated financial entities in 2018 to cease certain services connected to virtual currencies. On March 4, 2020, the Supreme Court of India set aside the circular. That ruling addressed the legality and proportionality of a particular banking restriction; it was not a universal statute declaring all cryptocurrency activities lawful. For businesses previously cut off from banking, however, a distinction that could sound procedural had practical importance.
Regulation also had a privacy cost that belonged in the same story as CoinJoin and self-custody. FATF guidance was aimed at covered service providers, not a rewriting of Bitcoin's protocol. Compliance information gathered at exchanges could link identities to ledger activity, while a person operating a wallet without an intermediary faced a different practical and legal situation. The distinction between a protocol and its regulated gateways was becoming sharper. [65]
Such changes do not form a single worldwide march toward acceptance. Some jurisdictions increased supervisory requirements, others restricted access, and others reversed earlier barriers. To write the history accurately requires identifying who was regulated, what rule actually changed, and what Bitcoin users could do afterward.
13 / Chapter 13
The Mining Business Meets Winter
Difficulty was designed to adjust. Debts, payroll, and electricity contracts were not.
A Bitcoin mining machine performs calculations to compete for the right to add the next block and collect its subsidy and transaction fees. Machines run because someone decides that expected revenue is worth the electricity, equipment, financing, space and maintenance. The network's difficulty adjustment changes the competitiveness of the mathematical task after each 2,016 blocks; it cannot forgive a company's bank loan or change its warehouse lease. That separation became painfully visible when Bitcoin's market price collapsed.
Contemporary data record a sharp fall in estimated network computing power in late 2018. On December 3, difficulty declined by about 15.1%, following a reduction of about 7.4% in November. BitMEX Research estimated that hashrate had fallen around 31% since early November and expressed the change as the approximate output of 1.3 million Antminer S9 units. That figure was a computational equivalence, not proof that investigators had counted 1.3 million individual machines being physically switched off. Reporters and analysts disagreed about the outlook, including warnings of a possible mining 'death spiral'. The actual adjustments demonstrated a more specific result: miners exited under pressure, blocks could slow before readjustment, and the remaining network continued operating. [45] [46]
There were losses beyond hash charts. Giga Watt, a Washington-state mining-hosting venture, filed a Chapter 11 petition on November 19, 2018. Its collapse gives the larger market episode a human and corporate dimension: customers, creditors, capital commitments, equipment and facilities had all been drawn into an industry whose expected economics had changed. It is not sufficient evidence to say the exchange-rate decline alone caused its bankruptcy. The court record, financing arrangements and operational history must be investigated independently for that specific causal judgment. [34]
Mining's geography also mattered. The search for cheap power moved machines toward places where electricity was abundant or seasonally inexpensive. China, especially major hydropower regions, occupied an important position in estimates of the period's mining activity. These estimates require care: the country observed in a mining-pool attribution, the location of a pool's headquarters, and the physical location of the machines contributing hashes need not match. Nor should a broad estimate for mining in 2020 be retroactively assigned to 2018. Energy use likewise depended on equipment efficiency, active capacity and electricity sources. The International Energy Agency's 2019 explanation explicitly treated those variables as interconnected rather than reducible to a single headline number. [47]
The stress did not end with a recovery in Bitcoin's dollar price. On March 26, 2020, following the global market shock, difficulty fell around 16%. Later, on November 3, it declined around 16.05%, amid reports of seasonal migration away from hydropower in China. These adjustments involved different immediate circumstances. A documentary should not flatten them into one unbroken 'capitulation' or assume that a lower difficulty means the Bitcoin network itself had failed. [48] [49]
What this history reveals is neither an effortless network indifferent to economics nor a fatal collapse narrowly avoided. It reveals a protocol that rebalances competition as miner participation changes, set within an industry whose firms can be highly fragile. Successful operation of Bitcoin did not guarantee successful operation of the companies that mined it.
14 / Chapter 14
A Different Monetary Argument
The same Bitcoin was described as cash, scarce savings and speculative gold.
In 2018, a person watching Bitcoin's price fall could understandably wonder what the asset was supposed to be. The original Bitcoin white paper had described electronic cash without a trusted intermediary. Yet a currency that had lost much of its exchange value in a year posed obvious difficulties for a merchant setting prices or a worker accepting a wage. Proponents increasingly emphasized scarcity, independent verification and savings. Critics asked how an asset subject to violent price changes could function as ordinary money. The dispute was already old; the bear market gave it a different setting.
Saifedean Ammous's The Bitcoin Standard, published in 2018, made an ambitious historical and economic argument for treating Bitcoin as a form of hard money. Its discussion connected Bitcoin's fixed issuance and resistance to discretionary change with theories of saving, monetary credibility and time preference. This was an influential articulation of a position, not empirical proof that Bitcoin had already become a reliable store of purchasing power. The book also belonged to a broader ecosystem of Bitcoin advocates who emphasized monetary rules over checkout speed. [74]
Academic economists did not speak in one voice. In a 2018 paper, Ammous argued that Bitcoin's relatively credible supply commitment supported its potential as a long-term store of value while volatile demand prevented cryptocurrencies from functioning readily as units of account. That distinction was useful precisely because it identified a tension, not a solved problem: predictable issuance does not make short-term market prices predictable. Other economists challenged the usefulness of decentralized cryptocurrencies for everyday payments and explored how central-bank electronic money could address different financial needs. [75] [76]
On July 11, 2019, Federal Reserve Chair Jerome Powell described Bitcoin during Senate testimony as being used more like a speculative alternative to gold than a payment medium. His remark was striking not because the Federal Reserve had endorsed Bitcoin, but because a senior central banker publicly recognized the store-of-value framing while doubting significant payment adoption. The statement was an observation about how he understood its use, not a formal classification or a forecast that Bitcoin would replace gold. [77]
That October, Federal Reserve Governor Lael Brainard supplied the counterweight. In a speech on digital currencies, she distinguished money's traditional functions: a medium of exchange, a store of value and a unit of account. She argued that Bitcoin's volatility, limited throughput and unpredictable transaction costs constrained its practical usefulness as a payment method. Her speech also addressed new stablecoin proposals, which promised more stable payments but introduced their own issuers and governance questions. The debate about digital money was therefore not one argument between Bitcoin and the existing financial system; it was a contest among monetary designs with different forms of trust. [78]
In June 2020, Federal Reserve Bank of New York researchers Michael Lee and Antoine Martin argued that Bitcoin's radical novelty lay less in being a wholly new kind of money than in allowing electronic exchange without the kind of trusted party customary in other systems. That distinction shifted attention from whether Bitcoin resembled gold or currency toward how it could move and settle an asset. It was another interpretation, not the institution's final verdict on Bitcoin's value. [79]
The chronology resists a tidy conversion story. Some people wanted to save outside an intermediary, others wanted more practical payments, and still others wanted an asset with rules no central bank could adjust. Lightning developers were addressing transactions; custody companies were addressing key control; financial institutions were building compliant access. These objectives could coexist while making different demands of users. The March 2020 liquidation cascade would soon expose the gap between describing Bitcoin as a refuge and observing its behavior under extreme market stress.
The question at the end of this argument was not which slogan had won. It was whether Bitcoin's fixed rules, emerging infrastructure and public market behavior could support the distinct roles people were assigning to it. That question remained unsettled as the third halving approached.
15 / Chapter 15
The Day Everything Was Sold
When the world demanded cash, Bitcoin's newest financial machinery added pressure of its own.
The night of March 12 into March 13, 2020, was not a normal episode in Bitcoin's familiar volatility. Financial markets around the world were struggling to price the growing economic shutdown triggered by COVID-19. Investors needed liquidity. Bitcoin fell violently alongside a broader wave of selling. It had often been described as an asset outside traditional monetary institutions, yet its traded price remained dependent on people, leveraged positions, exchanges, collateral and access to cash.
Coin Metrics' March 24 contemporary reconstruction records two severe stages: a fall from approximately $7,300 to $5,690 during an hour on March 12, followed by a second fall from around $5,800 to $3,900 overnight into March 13. These are reference-rate observations, not a universal intraday low on every exchange. That precision matters in a fragmented global market, where different venues could trade at different prices and where liquidations could accelerate a fall. [50]
BitMEX was central to the second episode. Its perpetual inverse swap let traders take leveraged exposure to Bitcoin's price while posting Bitcoin as margin. Once a position's collateral became insufficient, an exchange-controlled liquidation engine could take it over and attempt to close it. The resulting sales could push prices down further and place more traders below required margin, producing a feedback loop. Coin Metrics reported approximately $1.1 billion in BitMEX contract liquidations over the relevant March 12–13 interval, with a contract representing one dollar of exposure. The figure refers to contract value, not a count of Bitcoin transferred on-chain. [50]
At 02:16 UTC on March 13, BitMEX's service suffered a disruption. The company subsequently said that DDoS attacks struck at 02:16 and again at 12:56 UTC. Coin Metrics observed that Bitcoin's price recovered sharply during the first interruption. The sequence raised a consequential question about whether forced selling at a dominant leveraged venue had intensified the market panic. It does not, by itself, establish that the exchange deliberately suspended trading to manipulate prices or prove the exact counterfactual price without the outage. A presentation submitted to the U.S. Commodity Futures Trading Commission's Technology Advisory Committee in July 2020 described the liquidation feedback mechanism while also emphasizing the role of extremely high leverage and exchange design. [51] [52]
The consequences were felt by people who did not write trading algorithms. A trader trying to add margin needed the exchange to accept funds and process orders when everyone else was demanding the same access. Someone holding Bitcoin as collateral faced demands that could force asset sales at precisely the worst price. A person relying on cold storage might have preferred the security of slower access in quiet markets but encountered a new constraint during a sudden margin call. The costs of trust and timing were no longer abstractions.
The crash did not demonstrate that Bitcoin's fixed supply schedule was false, or that the network had ceased to validate transactions. Nor did its later price recovery prove that it was already a dependable safe haven in a short-term crisis. It exposed the collision between a predictable monetary protocol and a financial market that had become vulnerable to many of the same pressures as other leveraged markets. That collision is an essential part of the period's maturation story.
16 / Chapter 16
The Scheduled Cut
An exact rule met an industry that could not make exact plans.
On May 11, 2020, Bitcoin reached block 630,000. The block subsidy declined from 12.5 BTC to 6.25 BTC. This was neither a vote of miners nor an intervention by a central bank. It followed the issuance schedule already enforced by the network. A future reader should distinguish the predictable rule from the uncertain economic consequences: miners knew when the subsidy would change, but not what price, fees, difficulty or competition would be in the weeks afterward.
Mining rewards combine the subsidy with transaction fees. Halving the subsidy did not necessarily halve every miner's total revenue or affect every machine in the same way, although it reduced the issuance component sharply. A machine with high electricity costs could be retired while a more efficient one stayed profitable. A facility might move to cheaper seasonal power rather than permanently close. The network would adjust difficulty in response to actual changes in work contributed by miners, but not instantaneously.
A contemporaneous second-quarter 2020 industry report recorded a large post-halving drop in observed hashrate followed by recovery before the end of June. It also discussed the movement of some mining operations to Sichuan for the wet season and the temporary elevation of fee revenue in May. These are observational and industry-reported explanations rather than a clean experiment that isolates the halving's effect from the March crash, equipment turnover, exchange prices or regional power conditions. [53]
The halving is therefore best presented beside the prior December 2018 and March 2020 difficulty shocks, not as a detached ceremonial countdown. In each case, economic conditions changed what miners could profitably do; only the subsidy halving had a pre-established block height. Difficulty subsequently responded to changes in actual mining participation. These are related mechanisms, but they should not be confused.
The reward reduction was important precisely because it combined absolute procedural certainty with uncertainty in the market around it. It tested which machines, firms and power arrangements could survive a smaller subsidy. It did not mechanically mandate a particular future Bitcoin price. The end-2020 story should therefore resist a tempting shortcut: Bitcoin's later rally is not proof that cutting issuance was its single or sufficient cause.
17 / Chapter 17
Bitcoin Goes on the Balance Sheet
The decisive change was not a forecast. It was the purchase.
On August 11, 2020, publicly traded software company MicroStrategy announced that it had purchased 21,454 BTC for approximately $250 million. Its SEC filing and August public announcement established an actual purchase under an adopted capital-allocation strategy. Rather than simply provide employees or customers access to Bitcoin, MicroStrategy was making Bitcoin an asset of its own corporate treasury. Its managers, shareholders, accountants and auditors now had to confront Bitcoin price exposure, custody and reporting as company concerns. [60]
This was a specific corporate action, not the completion of a worldwide institutional transformation. A large public company taking such a position could influence how other executives discussed treasury assets. It did not establish that Bitcoin was suitable for every company, that later purchases would all follow the same design, or that the market had endorsed the approach. The company had already publicly described its August 11 transaction in terms of a primary treasury reserve asset. A separate September SEC filing recorded the purchase of an additional 16,796 BTC and increased total holdings to 38,250 BTC. The August strategy announcement and the September follow-on acquisition should not be collapsed into a single transaction. [60] [61]
Square provided a second, importantly different example. On October 8 it announced a completed purchase of approximately 4,709 BTC for $50 million. The company's existing Bitcoin activity in consumer payments made its treasury decision part of a wider strategy. Square's stated reasons emphasized economic empowerment and participation in an evolving monetary system. The evidence for its historical significance is not simply the corporate rhetoric but the fact that real funds had been converted into Bitcoin and assigned to a long-term balance-sheet position.
These decisions made a previously mostly theoretical question practical: what obligations arise when a public company's treasury contains an asset that trades continuously, is protected through digital key management and can undergo extraordinary volatility? The answers were still developing. The change was that the question now had prominent, documented real-world cases.
18 / Chapter 18
Bitcoin Outside the Boardroom
Three communities encountered the same network through different pressures.
By 2020, corporate custody and treasury purchases were making Bitcoin more legible to financial institutions. Yet Bitcoin was also being tested in settings where access to money was neither a portfolio decision nor an abstract technical debate. The most revealing examples are not proof of a single global adoption wave. They show different motivations, intermediaries, and practical limitations.
El Zonte: trying to circulate money locally. On January 13, 2020, Colin Harper reported from the emerging Bitcoin Beach initiative in El Salvador, describing Michael Peterson's work with young people in El Zonte and Punta Mango. This is a contemporary record—not merely an organizer's recollection published after El Salvador's 2021 legal-tender decision. Reporting in July 2020 described the experiment continuing through the economic disruption of the COVID-19 pandemic. Donations and local work payments were intended to support spending within the community, making circulation itself part of the experiment. [80] [81]
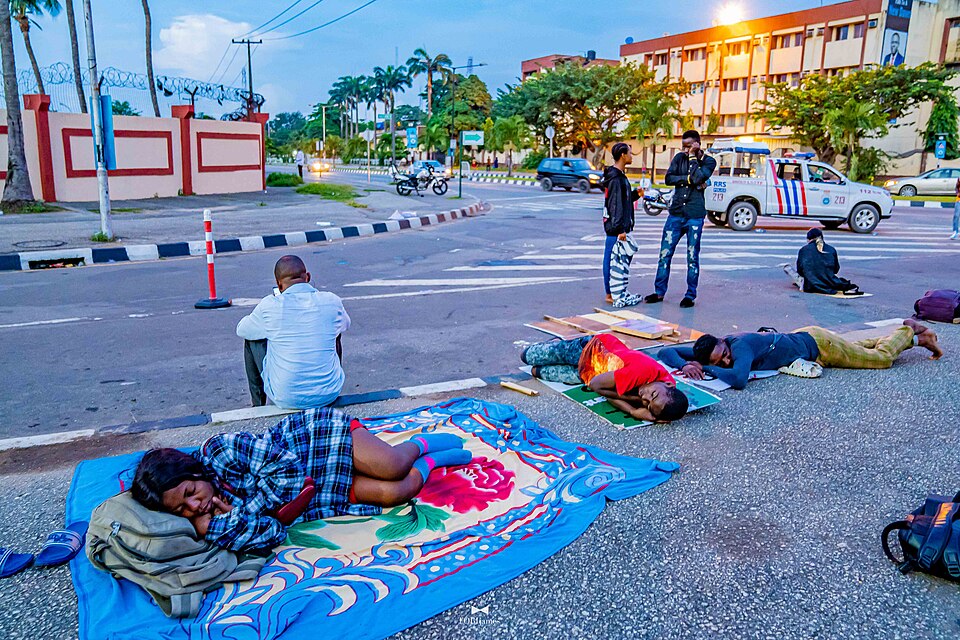
Lagos · October 9, 2020 · Historical photograph
Lagos, October 2020
Protesters in Lagos, Nigeria, October 9, 2020. The scene does not identify anyone pictured as a Bitcoin donor or recipient.
TobiJamesCandids · CC BY-SA 4.0 · Original file & provenance

Photograph date and reproduction
File record: October 9, 2020, 06:17:54; uploaded the same day at 20:37. Retrieved 2026-11-01. Uncropped source image at Wikimedia supplied resolution. No Monedial retouching or reconstruction. No endorsement is implied.
These reports establish that activity existed during the Current's period. They do not independently establish the fraction of El Zonte residents who used Bitcoin regularly or demonstrate that the village economy had become self-sustaining. Accounts about the origin of an anonymous donation also rely substantially on information supplied by participants, and should be attributed accordingly. Later stories about nationwide adoption cannot be moved backward into 2019 or 2020.
Venezuela: an alternative amid monetary distress. Venezuela offered a different motive. With an unstable bolivar and competing exchange rates, access to dollars and other value-transfer mechanisms became consequential. Bitcoin-denominated transactions on peer-to-peer platforms created an observable market, though the volumes reflected platform use rather than all monetary activity. An October 2020 research report by Arcane Research estimated that Venezuela accounted for 42 percent of the Latin American peer-to-peer volume covered by its methodology; it described a peak in weekly Venezuelan volume around spring 2019 and lower volumes by mid-2020. These figures are estimates from particular venues, not a census of Venezuelan Bitcoin ownership or evidence that Bitcoin replaced the bolivar in shops. [82]
A Bitcoin buyer in Venezuela could be seeking remittance access, speculative profit, a temporary bridge into another currency, or protection against restrictions. Individual transactions do not reveal motive. Moreover, exchange accounts and counterparties could still impose identity checks or create counterparty risk. The example matters because Bitcoin became one of the monetary options people investigated under severe local pressures, not because an entire country demonstrably adopted it as daily cash.
Nigeria: civil-society funds and the limits of transparency. In October 2020, the Feminist Coalition publicly organized funding for the peaceful #EndSARS protest movement. Its own site preserves statements issued during October and a later audit and financial reconciliation. Bitcoin became one channel for receiving support when organizers encountered practical barriers to conventional payment processing. The coalition's records provide evidence of receiving and converting Bitcoin, while also illustrating that receipt in Bitcoin was only one stage in paying expenses denominated in naira. [58] [59] [83]
The accounting material also documented the difficulty of transaction timing. An outbound Bitcoin transaction initiated in November 2020 was not confirmed until March 2021 after a low transaction fee. That fact became available retrospectively and should not be presented as knowledge the organizers held in October. The coalition also withheld one transaction identifier on privacy grounds, describing concern that publishing it could expose donor activity. A public ledger and a public-accountability obligation were not always easy to reconcile. [59]
The three settings produced different questions. El Zonte asked whether people could earn and spend Bitcoin within a community; Venezuela showed trading around an unstable local monetary system; Nigeria demonstrated an alternative fundraising rail during political protest. Each depended on people and institutions outside the consensus rules—organizers, exchanges, wallet operators, merchants or cash-conversion partners. None proves universal adoption, but together they prevent the history of 2018–2020 from becoming a narrative written only from trading desks and engineering offices.
19 / Chapter 19
A Door, Not the Destination
By December 2020, the possibilities had expanded. The unresolved questions had too.
Bitcoin had spent three years being tested in public, sometimes harshly. Its price collapsed, its most important software encountered a serious vulnerability, privacy tools encountered the limits of traceability, mining firms faced punishing competition and custodians exposed clients to forms of loss that Bitcoin's protocol could not prevent. The persistence of the network is not evidence that these harms were imaginary. They belong in any meaningful description of what Bitcoin had become.
At the same time, there had been changes whose historical significance did not depend on enthusiastic slogans. Software implemented existing SegWit capabilities. Lightning's early mainnet implementations opened the possibility of off-chain payments, while forcing users to learn about liquidity and channel security. PSBT, descriptors and related work made secure transaction construction more flexible. Privacy developers challenged common surveillance assumptions, without eliminating tracking. Miners were forced to adapt as difficulty and economics changed. In very different places, people put Bitcoin into local fundraising, remittance, trading and merchant experiments.
PayPal's October 2020 announcement and November U.S. rollout introduced Bitcoin exposure to a large consumer platform. Yet its service operated through an intermediary, and its announced merchant-payments plans were not equivalent to merchants directly accepting on-chain Bitcoin. Other institutions had built custody and market infrastructure, while MicroStrategy and Square disclosed completed purchases that placed Bitcoin on corporate balance sheets. These shifts showed the network entering traditional financial arrangements while leaving open the problem of who controlled the keys and the user's ability to leave a platform. [21]
Technical work also pointed past the close of 2020. Schnorr signatures and Taproot moved from proposals through extensive specification and implementation review; validation code had been merged, but the network had not activated Taproot. That happened in November 2021 and belongs to the later timeline of its history, not to an imagined 2020 deployment. [22] [23] [37] [38]
One useful way to test the entire period is to ask what became independently verifiable by the end of it. Users could verify transactions using Bitcoin software, but not an exchange's hidden balance sheet. They could validate the fixed subsidy rule, but not guarantee a miner's solvency. They could operate Lightning channels, but not assume liquidity or reliable channel recovery. They could receive a Bitcoin donation, but might still need an intermediary to convert it for immediate local expenses. Institutional access expanded, but it did not always extend independent control to the customer.
The meaning of the bear market years was not that everyone else was wrong and a hidden victory was inevitable. It was that Bitcoin became a more elaborate system of choices—between direct control and convenience, public verification and financial privacy, predictable rules and unpredictable financial consequences. The world could no longer understand it only as a price that had once surged and then fallen. Nor could Bitcoin's advocates seriously describe the next phase without confronting what had gone wrong.
photograph · 2020-10-09
Lagos, October 2020
Protesters in Lagos, Nigeria, October 9, 2020. The scene does not identify anyone pictured as a Bitcoin donor or recipient.
Explore the artifact ↗TobiJamesCandids, CC BY-SA 4.0, via Wikimedia Commons · CC BY-SA 4.0. Reduced-size reproduction.
Sources & further investigation
Primary documents
- P01 · Bitcoin Core, 0.16.0 Released, 26 February 2018
Source provenance
Bitcoin Core, 0.16.0 Released, 26 February 2018 — Source link
- P02 · Lightning Labs, Announcing our first Lightning mainnet release, lnd 0.4-beta!, 15 March 2018
Source provenance
Lightning Labs, Announcing our first Lightning mainnet release, lnd 0.4-beta!, 15 March 2018 — Source link
- P03 · Bitcoin Optech, Announcing Bitcoin Optech, 20 July 2018
Source provenance
Bitcoin Optech, Announcing Bitcoin Optech, 20 July 2018 — Source link
- P04 · Bitcoin Core, Disclosure of CVE-2018-17144, 20 September 2018
Source provenance
Bitcoin Core, Disclosure of CVE-2018-17144, 20 September 2018 — Source link
- P05 · Bitcoin Core, 0.17.0 release documentation
Source provenance
Bitcoin Core, 0.17.0 release documentation — Source link
- P06 · BIP 174, Partially Signed Bitcoin Transaction Format
Source provenance
BIP 174, Partially Signed Bitcoin Transaction Format — Source link
- P07 · Blockstream, Launch of the Liquid Network, 10 October 2018
Source provenance
Blockstream, Launch of the Liquid Network, 10 October 2018 — Source link
- P09 · BTCPay Server, Announcing the BTCPay Server Foundation, 14 September 2019
Source provenance
BTCPay Server, Announcing the BTCPay Server Foundation, 14 September 2019 — Source link
- P10 · Binance, Security Breach Update, 7 May 2019
Source provenance
Binance, Security Breach Update, 7 May 2019 — Source link
- P11 · ICE Futures U.S., September 2019 Bakkt Futures Launch Notice
Source provenance
ICE Futures U.S., September 2019 Bakkt Futures Launch Notice — Source link
- P18 · MicroStrategy company press release, 11 August 2020, via Nasdaq
Source provenance
MicroStrategy company press release, 11 August 2020, via Nasdaq — Source link
- P20 · Square, Invests $50 Million in Bitcoin, 8 October 2020
Source provenance
Square, Invests $50 Million in Bitcoin, 8 October 2020 — Source link
- P21 · PayPal corporate release, 21 October 2020, with 12 November availability update
Source provenance
PayPal corporate release, 21 October 2020, with 12 November availability update — Source link
- P22 · BIP 342, Validation of Taproot Scripts
Source provenance
BIP 342, Validation of Taproot Scripts — Source link
- P25 · Bitcoin Optech Newsletter #70, LN simplified commitments, 30 October 2019
Source provenance
Bitcoin Optech Newsletter #70, LN simplified commitments, 30 October 2019 — Source link . Status: contemporaneous.
- P26 · Bitcoin Optech Newsletter #29, C-Lightning security upgrade, 15 January 2019
Source provenance
Bitcoin Optech Newsletter #29, C-Lightning security upgrade, 15 January 2019 — Source link . Status: contemporaneous.
- P27 · Bitcoin Optech Newsletter #119, LND security upgrade warning, 14 October 2020
Source provenance
Bitcoin Optech Newsletter #119, LND security upgrade warning, 14 October 2020 — Source link . Status: contemporaneous warning.
- P28 · Bitcoin Optech Newsletter #121, Full disclosures of two LND vulnerabilities, 28 October 2020
Source provenance
Bitcoin Optech Newsletter #121, Full disclosures of two LND vulnerabilities, 28 October 2020 — Source link . Status: contemporaneous disclosure coverage.
- P29 · Bitcoin Optech Newsletter #45, Output script descriptors in Bitcoin Core 0.18, 7 May 2019
Source provenance
Bitcoin Optech Newsletter #45, Output script descriptors in Bitcoin Core 0.18, 7 May 2019 — Source link . Status: contemporaneous.
- P30 · Bitcoin Optech Newsletter #61, Miniscript request for comments, 28 August 2019
Source provenance
Bitcoin Optech Newsletter #61, Miniscript request for comments, 28 August 2019 — Source link . Status: contemporaneous.
- P34 · Giga Watt, Inc., bankruptcy case information, Chapter 11 petition date 19 November 2018
Source provenance
Giga Watt, Inc., bankruptcy case information, Chapter 11 petition date 19 November 2018 — Source link . Status: court-administrator case portal; causes of insolvency are not established merely by filing date.
- P37 · Bitcoin Core PR Review Club, Meetings by Component (2020 Taproot code review schedule)
Source provenance
Bitcoin Core PR Review Club, Meetings by Component (2020 Taproot code review schedule) — Source link . Status: primary developer meeting index.
- P39 · Wasabi Wallet initial release history, carried forward from [P08]; version 1.0, October 31, 2018. See original P08 for precise URL.
Source provenance
Wasabi Wallet initial release history, carried forward from [P08]; version 1.0, October 31, 2018. See original P08 for precise URL.
- P40 · Samourai Whirlpool public beta documentation
Source provenance
Samourai Whirlpool public beta documentation — Source link — project's description; feature claims are not independent efficacy validation.
- P43 · Bitcoin Optech newsletter #94, BTCPay Server payjoin, April 22, 2020
Source provenance
Bitcoin Optech newsletter #94, BTCPay Server payjoin, April 22, 2020 — Source link — contemporaneous technical implementation report.
- P44 · Bitcoin Optech newsletter #104, BIP78 specification, July 1, 2020
Source provenance
Bitcoin Optech newsletter #104, BIP78 specification, July 1, 2020 — Source link — contemporaneous BIP merge stage, distinct from April deployment.
- P46 · Aaron van Wirdum and Colin Harper, Bitcoin's Network Just Experienced Its Second Largest Downward Adjustment, December 3, 2018
Source provenance
Aaron van Wirdum and Colin Harper, Bitcoin's Network Just Experienced Its Second Largest Downward Adjustment, December 3, 2018 — Source link — contemporary independent corroboration.
- P47 · International Energy Agency, Bitcoin energy use — mined the gap, 2019
Source provenance
International Energy Agency, Bitcoin energy use — mined the gap, 2019 — Source link — dated sector analysis; energy input methodology must be preserved.
- P50 · Coin Metrics, The BitMEX Liquidation Spiral, March 24, 2020
Source provenance
Coin Metrics, The BitMEX Liquidation Spiral, March 24, 2020 — Source link — contemporary quantitative market analysis.
- P51 · BitMEX, How We Are Responding to the 13 March DDoS Attacks, March 16, 2020
Source provenance
BitMEX, How We Are Responding to the 13 March DDoS Attacks, March 16, 2020 — Source link — primary company incident account; claims of mechanism attributed to operator.
- P56 · Jackie Johnson, Bitcoin and Venezuela's Unofficial Exchange Rate, Ledger, 2019
Source provenance
Jackie Johnson, Bitcoin and Venezuela's Unofficial Exchange Rate, Ledger, 2019 — Source link — research of peer-to-peer Bitcoin trading data, not a census of users.
- P58 · Feminist Coalition, #EndSARS project and contemporaneous statement archive
Source provenance
Feminist Coalition, #EndSARS project and contemporaneous statement archive — Source link — first-party account of 2020 fundraising and later reconciliation.
- P59 · Feminist Coalition, March 12, 2021 financial reconciliation, especially Bitcoin transaction discussion
Source provenance
Feminist Coalition, March 12, 2021 financial reconciliation, especially Bitcoin transaction discussion — Source link — retrospective primary accounting of 2020 sale and a 2021 on-chain confirmation; do not imply that transaction confirmed in 2020.
- P60 · MicroStrategy, Form 8-K, August 11, 2020
Source provenance
MicroStrategy, Form 8-K, August 11, 2020 — Source link — completed 21,454 BTC purchase, not merely an intention.
- P61 · MicroStrategy, Form 8-K, September 15, 2020
Source provenance
MicroStrategy, Form 8-K, September 15, 2020 — Source link — records another 16,796 BTC acquired September 14; company total 38,250 BTC. This filing supersedes earlier imprecise descriptions of the September stage.
- P63 · Stütz and colleagues, Adoption and Actual Privacy of Decentralized CoinJoin Implementations in Bitcoin
Source provenance
Stütz and colleagues, Adoption and Actual Privacy of Decentralized CoinJoin Implementations in Bitcoin — Source link — version and data observation period should be identified independently; the abstract includes data through February 28, 2022.
- P66 · PayPal, October 21, 2020 announcement with November 12 rollout update
Source provenance
PayPal, October 21, 2020 announcement with November 12 rollout update — Source link — explicitly distinguishes crypto access from future fiat-settled merchant payments.
- P67 · Coin Metrics, Assessing the Long-Term Fallout from Crypto's Black Thursday, April 21, 2020
Source provenance
Coin Metrics, Assessing the Long-Term Fallout from Crypto's Black Thursday, April 21, 2020 — Source link — contemporary differentiated analysis of exchange liquidity, fees, and broader market effects.
- P68 · Casa, Casa 2019 in Review and a Personal Update (2019 retrospective)
Source provenance
Casa, Casa 2019 in Review and a Personal Update (2019 retrospective), Source link . Note: same source as P69 below; P68 retained as audit alias, do not double-count.
- P69 · Casa, Casa 2019 in Review and a Personal Update
Source provenance
Casa, Casa 2019 in Review and a Personal Update, Source link . First-party product chronology; growth statistics are company-reported.
- P70 · Casa, Casa's Focus on Bitcoin Security (January 2020)
Source provenance
Casa, Casa's Focus on Bitcoin Security (January 2020), Source link . Strategy change from hardware nodes to Keymaster; announcement, not proof of long-term outcome.
- P74 · Wiley / O'Reilly bibliographic record, The Bitcoin Standard
Source provenance
Wiley / O'Reilly bibliographic record, The Bitcoin Standard, Source link . Book published 2018; philosophical claims attributed to author.
- P83 · Feminist Coalition, End SARS project archive
Source provenance
Feminist Coalition, End SARS project archive, Source link . Original organization index to October statements and later audit; distinguish contemporary from retrospective evidence.
- End SARS protest in Lagos, Nigeria
Source provenance
Government & legal records
- P13 · FATF, Risk-Based Approach to Virtual Assets and VASPs, 21 June 2019
Source provenance
FATF, Risk-Based Approach to Virtual Assets and VASPs, 21 June 2019 — Source link
- P14 · Supreme Court of India, Internet and Mobile Association of India v. Reserve Bank of India, 4 March 2020
Source provenance
Supreme Court of India, Internet and Mobile Association of India v. Reserve Bank of India, 4 March 2020 — Source link
- P19 · MicroStrategy, 14 September 2020 Form 8-K treasury policy (original SEC filing)
Source provenance
MicroStrategy, 14 September 2020 Form 8-K treasury policy (original SEC filing) — Source link
- P32 · Ontario Securities Commission, QuadrigaCX: A Review by Staff of the Ontario Securities Commission, released 11 June 2020
Source provenance
Ontario Securities Commission, QuadrigaCX: A Review by Staff of the Ontario Securities Commission, released 11 June 2020 — Source link . Status: authoritative investigative staff conclusions, not adjudicated findings.
- P33 · Ontario Securities Commission, Where Did the Funds Go?
Source provenance
Ontario Securities Commission, Where Did the Funds Go? — Source link . Status: authoritative breakdown; Canadian-dollar figures and categories must be retained.
- P52 · ErisX, presentation to CFTC Technology Advisory Committee, July 16, 2020
Source provenance
ErisX, presentation to CFTC Technology Advisory Committee, July 16, 2020 — Source link — industry presentation hosted by federal regulator, not a formal CFTC agency finding. Slide 6 reproduces March price/liquidations and service interruption.
- P62 · Ontario Securities Commission, QuadrigaCX: A Review by Staff
Source provenance
Ontario Securities Commission, QuadrigaCX: A Review by Staff — Source link — staff findings and explicit limitation that these are not a tribunal's adjudicated findings.
- P65 · FATF, Guidance for a Risk-Based Approach to Virtual Assets and Virtual Asset Service Providers, June 21, 2019
Source provenance
FATF, Guidance for a Risk-Based Approach to Virtual Assets and Virtual Asset Service Providers, June 21, 2019 — Source link — official 2019 guidance; present provider obligations accurately and do not backfill later revisions.
- P76 · Federal Reserve Bank of St. Louis, Berentsen & Schär, The Case for Central Bank Electronic Money and the Non-case for Central Bank Cryptocurrencies (2018)
Source provenance
Federal Reserve Bank of St. Louis, Berentsen & Schär, The Case for Central Bank Electronic Money and the Non-case for Central Bank Cryptocurrencies (2018), Source link . Contrasting argument about money and payment structure.
- P77 · U.S. Senate hearing record, Jerome Powell testimony, 11 July 2019 (text mirrored)
Source provenance
U.S. Senate hearing record, Jerome Powell testimony, 11 July 2019 (text mirrored), Source link . Congressional hearing is archival priority; PDF official source Source link .
- P78 · Federal Reserve Board, Lael Brainard, Digital Currencies, Stablecoins, and the Evolving Payments Landscape, 16 October 2019
Source provenance
Federal Reserve Board, Lael Brainard, Digital Currencies, Stablecoins, and the Evolving Payments Landscape, 16 October 2019, Source link . Original speech.
- P79 · Federal Reserve Bank of New York, Lee & Martin, Bitcoin Is Not a New Type of Money, 18 June 2020
Source provenance
Federal Reserve Bank of New York, Lee & Martin, Bitcoin Is Not a New Type of Money, 18 June 2020, Source link . Authors' argument, not federal monetary-policy determination.
Contemporary reporting
- P12 · Bloomberg, Deliverable Futures Start Trading, 23 September 2019
Source provenance
Bloomberg, Deliverable Futures Start Trading, 23 September 2019 — Source link
- P15 · CoinDesk, Bitcoin's Crash Triggers Over $700M in Liquidations, 12 March 2020
Source provenance
CoinDesk, Bitcoin's Crash Triggers Over $700M in Liquidations, 12 March 2020 — Source link
- P41 · TFTC, contemporary report on the open-sourcing of Samourai Dojo, June 3, 2019
Source provenance
TFTC, contemporary report on the open-sourcing of Samourai Dojo, June 3, 2019 — Source link — contemporary report; notes remaining trust and setup considerations.
- P48 · The Block, March 26, 2020 mining difficulty reduction
Source provenance
The Block, March 26, 2020 mining difficulty reduction — Source link — contemporary reporting.
- P49 · The Block, November 3, 2020 mining difficulty reduction
Source provenance
The Block, November 3, 2020 mining difficulty reduction — Source link — contemporary reporting; geographic/seasonal attribution is reportage, not an exact machine census.
- P72 · The Block, Casa is Changing; Kicking off with Two New Products (28 February 2019)
Source provenance
The Block, Casa is Changing; Kicking off with Two New Products (28 February 2019), Source link . Independent reporting on offerings and ambitions.
- P80 · Bitcoin Magazine, Colin Harper, On the Coast of El Salvador, Bitcoin Is Becoming the Standard, 13 January 2020
Source provenance
Bitcoin Magazine, Colin Harper, On the Coast of El Salvador, Bitcoin Is Becoming the Standard, 13 January 2020, Source link . Contemporary report; publisher blocks some automated full-page retrieval.
- P81 · Forbes, Tatiana Koffman, This El Salvador Village Adopts Bitcoin As Money, 14 July 2020
Source provenance
Forbes, Tatiana Koffman, This El Salvador Village Adopts Bitcoin As Money, 14 July 2020, Source link . Contemporary report; caution on organizer-origin claims.
Scholarship & later histories
- P08 · Wasabi Wallet documentation, project history (retrospective source)
Source provenance
Wasabi Wallet documentation, project history (retrospective source) — Source link
- P16 · CoinDesk Research, Q1 2020 Quarterly Review (historic research report)
Source provenance
CoinDesk Research, Q1 2020 Quarterly Review (historic research report) — Source link
- P17 · Bitcoin.org, halving history (retrospective explanatory reference)
Source provenance
Bitcoin.org, halving history (retrospective explanatory reference) — Source link
- P23 · Bitcoin Core GitHub implementation inventory, Taproot mainnet activation version note (retrospective)
Source provenance
Bitcoin Core GitHub implementation inventory, Taproot mainnet activation version note (retrospective) — Source link
- P24 · Bitcoin Optech, Anchor outputs (living topic index with 2018–2020 source trail)
Source provenance
Bitcoin Optech, Anchor outputs (living topic index with 2018–2020 source trail) — Source link . Status: retrospective index; specific historical claims should link to dated 2019–2020 newsletters before final publication.
- P31 · Bitcoin Optech, Hardware wallet interface (HWI) (living topic index with dated 2019–2020 notes)
Source provenance
Bitcoin Optech, Hardware wallet interface (HWI) (living topic index with dated 2019–2020 notes) — Source link . Status: retrospective index; do not import 2021 integration capabilities into 2019.
- P35 · CBS / 60 Minutes, Bitcoin Beach, 10 April 2022
Source provenance
CBS / 60 Minutes, Bitcoin Beach, 10 April 2022 — Source link . Status: retrospective participant interviews about 2019 origins.
- P36 · VanEck, Dispatch from El Salvador’s Bitcoin Beach (2021)
Source provenance
VanEck, Dispatch from El Salvador’s Bitcoin Beach (2021) — Source link . Status: retrospective first-person field reporting with organizer accounts; independent contemporaneous 2019 documentation remains desirable.
- P38 · Bitcoin Optech, Taproot living technical history and dated source trail
Source provenance
Bitcoin Optech, Taproot living technical history and dated source trail — Source link . Status: retrospective index linking 2020 implementation and 2021 activation as separate stages.
- P42 · Rainer Stütz et al., Adoption and Actual Privacy of Decentralized CoinJoin Implementations in Bitcoin, first posted September 2021
Source provenance
Rainer Stütz et al., Adoption and Actual Privacy of Decentralized CoinJoin Implementations in Bitcoin, first posted September 2021 — Source link — retrospective academic measurement extending through 2022; cannot be presented as 2020 adoption figures.
- P45 · BitMEX Research, The Price Crash & The Impact on Miners, December 9, 2018
Source provenance
BitMEX Research, The Price Crash & The Impact on Miners, December 9, 2018 — Source link — contemporary estimated hashrate/difficulty, not census of physical hardware.
- P53 · CoinGecko, 2020 Q2 Cryptocurrency Report, pages on halving/miner hashrate
Source provenance
CoinGecko, 2020 Q2 Cryptocurrency Report, pages on halving/miner hashrate — Source link — sector report; chart estimates and causal attributions must be qualified.
- P54 · Roman Martínez first-person retrospective account of Bitcoin Beach
Source provenance
Roman Martínez first-person retrospective account of Bitcoin Beach — Source link — organizer testimony published after 2020; government-hosted, advocacy-adjacent context.
- P55 · Bitcoin Beach project account
Source provenance
Bitcoin Beach project account — Source link — retrospective community project account; year-one merchant count not established independently.
- P57 · Looking for a safe-haven in a crisis-driven Venezuela, Transforming Government, May 2020
Source provenance
Looking for a safe-haven in a crisis-driven Venezuela, Transforming Government, May 2020 — Source link — academic analysis with sample-period limitations.
- P64 · Fidelity Digital Assets, historical milestones
Source provenance
Fidelity Digital Assets, historical milestones — Source link — company-supplied retrospective chronology of announcement in 2018 and New York trust charter in 2019; seek contemporary NYDFS record for publication.
- P71 · Bitcoin Core BIP implementation mapping
Source provenance
Bitcoin Core BIP implementation mapping, Source link . Retrospective page maps BIP174 PSBT operations to Bitcoin Core v0.17.0; validate against contemporaneous release notes.
- P73 · Specter Desktop, public project documentation
Source provenance
Specter Desktop, public project documentation, Source link . Retrospective and mutable; do not claim the currently listed supported hardware existed or worked in 2020.
- P75 · Saifedean Ammous, Can cryptocurrencies fulfil the functions of money? (2018)
Source provenance
Saifedean Ammous, Can cryptocurrencies fulfil the functions of money? (2018), Source link . Published academic interpretation, not consensus.
- P82 · Arcane Research, The State of Crypto: The P2P Market, October 2020
Source provenance
Arcane Research, The State of Crypto: The P2P Market, October 2020, Source link . Page 28 examines Venezuelan peer-to-peer volumes; venue sample only.